FTSE Surges Over 2% as U.S. Midterm Results, Softening Yields, and Mining Rally Ignite Broad Buying
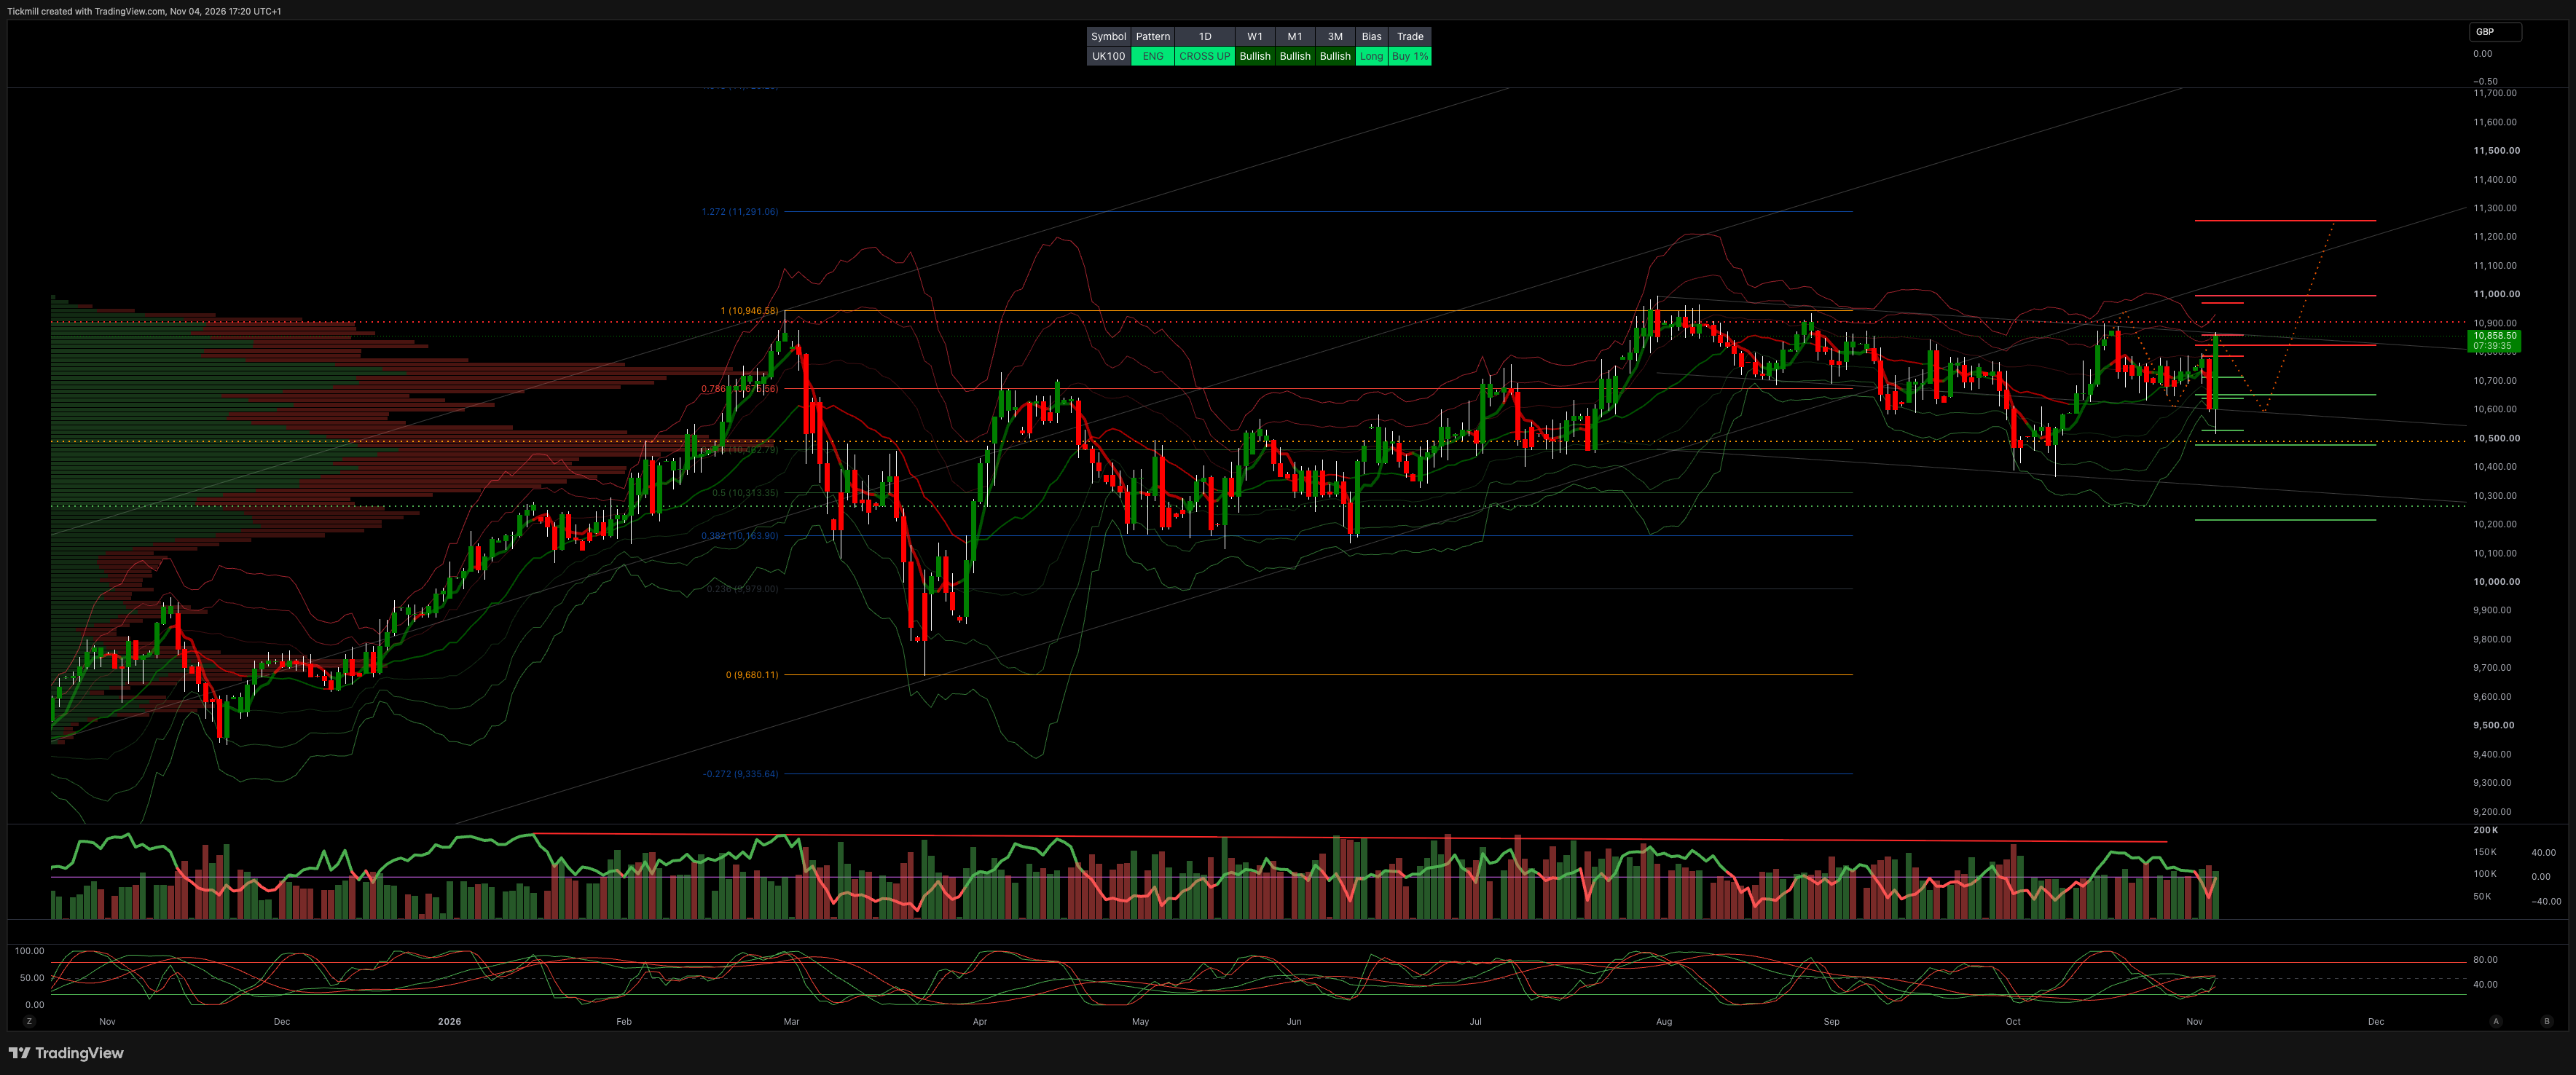
FTSE Surges Over 2% as U.S. Midterm Results, Softening Yields, and Mining Rally Ignite Broad Buying
London’s benchmark FTSE 100 rallied sharply on Wednesday, surging alongside broader European markets following the dramatic outcome of the U.S. midterm elections. After tracking more than 130 points higher past midday, aggressive buying extended the top flight's advance to roughly 2.4% into the afternoon, comfortably pushing the index beyond the 10,850 level. Easing government bond yields, cooling crude oil prices, robust domestic services expansion, and blockbuster corporate results provided a powerful catalyst for risk appetite across financial, mining, and tech-adjacent counters.
Broad-based buying propelled multiple sectors to multi-week highs. Natural resource heavyweights surged as global sentiment cleared: precious metals producers Fresnillo and Endeavour Mining jumped 6.8% and 6.5%, respectively, while copper major Antofagasta climbed 5.2%. Anglo American advanced 4.1%, Rio Tinto gained 2.7%, and Glencore added 2.5%. Financials experienced exceptional demand: Lion Finance surged 7.7% after delivering a 22.6% revenue jump to GEL 1.145 billion and net profit of GEL 661.88 million (GEL 15.42 per share vs. GEL 12.58 prior year). Rate-sensitive banking heavyweights posted widespread gains of over 4% to 5%, led by Standard Chartered (+5.2%), HSBC Holdings (+4.7%), Barclays (+4.3%), and 4% surges across both Lloyds Banking Group and NatWest Group. Marks & Spencer rose over 2% after delivering a sharp increase in half-year earnings despite sector-wide cost inflation, while gains of 2% to 3% were logged across Burberry Group, St. James's Place, Associated British Foods, AutoTrader Group, ICG, Games Workshop, Aberdeen Group, and Pershing Square Holdings. Global technology names also drew an indirect bid following AMD's record Q3 AI chip revenue.
Conversely, individual earnings reactions, sliding crude prices, and defense profit-taking capped select counters. Engineering group Weir tanked 7.6% to lead blue-chip decliners, succumbing to profit-taking despite a year-on-year rise of 8% in Q3 group orders. Outside the main index, ticketing platform Trainline tumbled 4% on weaker first-half profits. Defense contractors saw tactical selling following the U.S. election outcome, with BAE Systems dropping 3.7% and Babcock International losing 1.9%. Energy producers also lagged the broader market as oil softened, sending Ithaca Energy down 2.7%, while Computacenter and Spirax Group slipped 2.0% and 1.4%, respectively.
Macro sentiment shifted decisively as investors digested the U.S. midterm election outcome, where Democrats took control of both houses of Congress. The unexpected sweep relieved immediate market concerns surrounding unilateral trade escalation, aggressive tech disruption, and runaway federal deficit expansions. Commodity markets saw front-month Brent crude futures drop as much as 1.4% to an intraday low of $101.55 a barrel before edging to $102.10, helping suppress broader input-cost worries.
On the domestic macroeconomic front, final survey data confirmed resilient momentum across the U.K. private sector. The S&P Global UK Services PMI rose to 52.8 in October from 52.1 in September, signaling the fastest services expansion since February on strengthening order books. Consequently, the UK Composite PMI climbed to an eight-month high of 52.9 (up from 52.0), providing a solid foundation of business activity ahead of Thursday's high-stakes Bank of England Monetary Policy Committee decision, where a 25-basis-point hike to 4.00% remains broadly anticipated.
Finish Line: U.K. equities mounted a powerful, broad-based relief rally as political clarity from the U.S. midterm elections, softening sovereign yields, and retreating energy prices triggered aggressive inflows into banks, miners, and retail heavyweights. While post-earnings pullbacks in Weir and defense names provided localized drag, the FTSE 100’s surge past 10,850 firmly realigns the benchmark toward the top of its macro trading range heading into Thursday’s BoE rate verdict.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!